Online estate planning is not the opposite of working with an attorney. You can meet a lawyer remotely, make informed decisions about your family, and complete a customized plan without traveling to an office. The meaningful comparison is self-service documents versus the advice, drafting, signing support, and implementation instructions included in a particular engagement.
If you are comparing an online trust vs. an attorney-guided estate plan, start with the decisions you need help making—not the number of documents in the package. A will or trust can be properly prepared yet still fail to accomplish a goal because an account beneficiary, a property title, or a child’s inheritance arrangement does something different.
What does “online estate planning” actually include?
The word “online” describes a delivery method. It does not tell you whether a lawyer will analyze your circumstances or who is responsible for work after the documents are prepared. Distinguish these three models when reading an offer.
1. Self-service document preparation
You answer questions and receive documents based on your responses. This can make basic planning vocabulary more approachable and help organize your wishes. The key question is whether the service includes individualized legal advice or primarily supplies document-generation tools.
Do not assume a product is unsuitable merely because it uses a questionnaire; attorneys use questionnaires too. Instead, identify who evaluates the answers, whether you can discuss an uncertain choice, and what happens when your circumstances fall outside the offered options.
2. Documents with limited attorney access
Some services combine forms with a consultation, document review, or a subscription offering access to attorneys. Those features can be useful, but the exact agreement matters. Ask whether counsel will review the entire plan, revise the documents, advise on account coordination, or answer only the specific questions you bring.
Confirm that the attorney is licensed in the relevant state, who the client is, what the representation covers, and when any subscription or update access ends. “Attorney access” and “a lawyer responsible for drafting my estate plan” are not necessarily the same service.
3. Direct attorney-guided virtual planning
You retain a law firm to discuss goals, recommend a structure, prepare the agreed documents, and guide the planning and signing process. Meetings can take place by video. You should still read the engagement agreement: an attorney-guided plan is not automatically an unlimited service or a promise to implement every asset transfer.
Carolina Estate Plan provides this third model for North Carolina and South Carolina families. See how virtual estate planning works.
Compare scope before comparing online trust prices
A lower price may reflect a narrower service, not an inferior document. A higher price does not establish that every task is included. Ask each provider the same questions and compare the written answers.
| Planning issue | Questions to ask any provider | Carolina Estate Plan’s approach |
|---|---|---|
| Document selection | Who helps me decide between a will-based and trust-based plan? Are incapacity documents included? | We discuss family, property, decision-makers, and goals before selecting the agreed estate-planning documents. |
| Fiduciary choices | Will someone explain the different jobs and discuss backups or conflicts? | We discuss guardian nominations, executor, trustee, financial agent, healthcare agent, and appropriate backups. |
| Signing | What instructions are included? Who coordinates the notary, and what witness arrangements must I make? | We provide execution guidance and coordinate mobile-notary signing. Document-specific witness and signing requirements still apply. |
| Trust funding | Does “funding” mean instructions, deeds, actual account transfers, or verification of completed transfers? | Trust-based plans include first-deed/primary-residence work and detailed asset-by-asset funding instructions. Clients carry out account retitling, beneficiary changes, and other transfers. |
| Questions and follow-up | What questions and revisions are covered before signing? What requires a later engagement or recurring payment? | The planning process includes discussion and document review before signing. Future changes and additional work should be confirmed separately; ongoing funding review is not included. |
Before paying, also ask about delivery format, access to completed documents, cancellation terms, and any charges for later changes. Do not compare a stand-alone will download with a complete trust-based engagement as if they were equivalent purchases.
For this firm’s offer and included work, start with flat-fee estate planning. Our North Carolina estate-planning cost guide explains additional quote-comparison questions without treating one firm’s fee as a statewide market average.
When a form may fit—and when advice matters
A person with straightforward wishes, capable adult beneficiaries receiving outright gifts, and a clear understanding of the applicable instructions may decide that a carefully selected self-service option fits the task and budget. That is a scope decision, not a guarantee of validity or suitability. Even an apparently simple estate can contain an account designation or family circumstance that changes the analysis.
If you cannot explain what happens to each major asset, who acts if you become incapacitated, and what happens if a beneficiary dies first, resolve those questions before treating any package as finished.
| Your situation | Why individualized advice becomes more valuable |
|---|---|
| Young children and life insurance | You need to distinguish who raises the children from who manages their inheritance, and coordinate the policy beneficiary with that arrangement. |
| A spouse and children from a previous relationship | Outright gifts, continuing trusts, spouse rights, and beneficiary designations can produce very different outcomes. |
| A beneficiary receiving means-tested benefits | An ordinary inheritance arrangement may affect eligibility; specialized advice is important before selecting a trust or beneficiary designation. |
| A home, rental property, or property in another state | Ownership, existing loans, local deed requirements, and the intended trust need to be considered together. |
| A business interest, disputed relationship, or substantial tax concern | Transfer restrictions, conflicts, and tax rules may require advice beyond an ordinary estate-planning package. |
Having one of these circumstances does not mean every family needs the same trust. It means the choice deserves analysis. If full-service planning is outside your budget, ask about a clearly defined limited engagement or available legal-assistance resources rather than assuming the only choices are an expensive package or no plan at all.
A practical example: two parents, a home, and two young children
Imagine two 38-year-old North Carolina parents with children ages four and two, a home, retirement accounts, and term life insurance. Their goal: choose people they trust to care for the children and avoid handing a large inheritance to a child before that child is ready.
This is a hypothetical, not a client story. It shows why the planning questions matter more than whether the meeting happens in an office.
Choose people for different jobs
The parents might want a sibling to raise the children because of shared values. A different person may be better suited to keeping records, investing, and deciding whether a distribution fits the trust’s terms. Guardian nomination and trustee selection are separate decisions. Under N.C. G.S. 35A-1225, a parent’s will recommendation is a strong guide in the absence of a surviving parent, but the clerk can make a different appointment in the child’s best interest.
Discuss backups and practical coordination. Who would handle an urgent expense? How would the caregiver request money from the trustee? A trusted relative is not automatically the right person for every fiduciary role.
Decide what “not too much, too soon” means
The parents could explore a trustee-managed arrangement allowing appropriate support while postponing outright control. They should discuss education, health needs, unequal needs between siblings, and what happens if a child dies before receiving the entire share.
Distribution ages are not the whole design. A trust that allows support before a later distribution age works differently from one that simply says “pay at 30.” A staged distribution may fit one family, while ongoing trustee discretion may better fit another.
Make the assets follow the plan
The parents then need to check how the home is titled and whom the insurance policy names. A trust provision about children’s inheritance does not, by itself, change an insurer’s beneficiary record. Retirement-account beneficiary choices have separate distribution rules and should not be copied from a life-insurance decision.
An attorney-guided process helps the parents make those choices with context. The parents still have implementation responsibilities. Explore the role of a living trust before deciding that a particular product or document count solves the problem.
Signing rules are document-specific in NC and SC
Using a form does not automatically make a document invalid, and paying an attorney does not excuse a defective signing. The applicable law and actual execution matter. Do not assume that a notary stamp, an electronic signature, or a video call is sufficient for every document.
North Carolina wills
For an ordinary attested written will, N.C. G.S. 31-3.3 requires the testator’s signature and at least two competent witnesses. The testator must sign in the witnesses’ presence or acknowledge the signature; the witnesses must sign in the testator’s presence. The statute permits the witnesses to be present separately and does not require them to sign in each other’s presence.
The separate self-proving procedure in G.S. 31-11.6 uses acknowledgments and witness affidavits before an authorized officer. Self-proof and the underlying execution requirements are different concepts. This summary addresses attested written wills, not every special form or cross-jurisdiction exception.
South Carolina wills
S.C. Code § 62-2-502 generally requires a written will signed by the testator, or at the testator’s direction and in the testator’s presence, and signed by at least two individuals who witnessed the signing or acknowledgment of the signature or will. The statute expressly identifies exceptions, including the choice-of-law provision in § 62-2-505.
South Carolina’s self-proving procedure appears separately in § 62-2-503. Do not substitute North Carolina signing instructions for a South Carolina document—or assume that one state’s affidavit is interchangeable with the other’s.
Trusts and other documents
Trust-creation requirements appear in N.C. G.S. 36C-4-402 and S.C. Code §§ 62-7-401 and 62-7-402. These address matters such as capacity, intent, beneficiaries, trustee duties, and methods of creation. South Carolina separately addresses a signed written declaration and written evidence for real-property trusts in § 62-7-401.
A will’s witness rule is not a universal rule for every trust, power of attorney, healthcare directive, or deed. Those documents have their own requirements. These statutes are not a do-it-yourself signing checklist; instructions should be matched to the actual documents and applicable law.
Trust funding: signing and transferring assets are different jobs
A signed trust does not automatically retitle your bank account, rewrite your insurance designation, or change the owner shown on a deed. Whether an asset is controlled by the trust depends on the relevant transfer, ownership, or beneficiary arrangement—not simply whether it appears on a list.
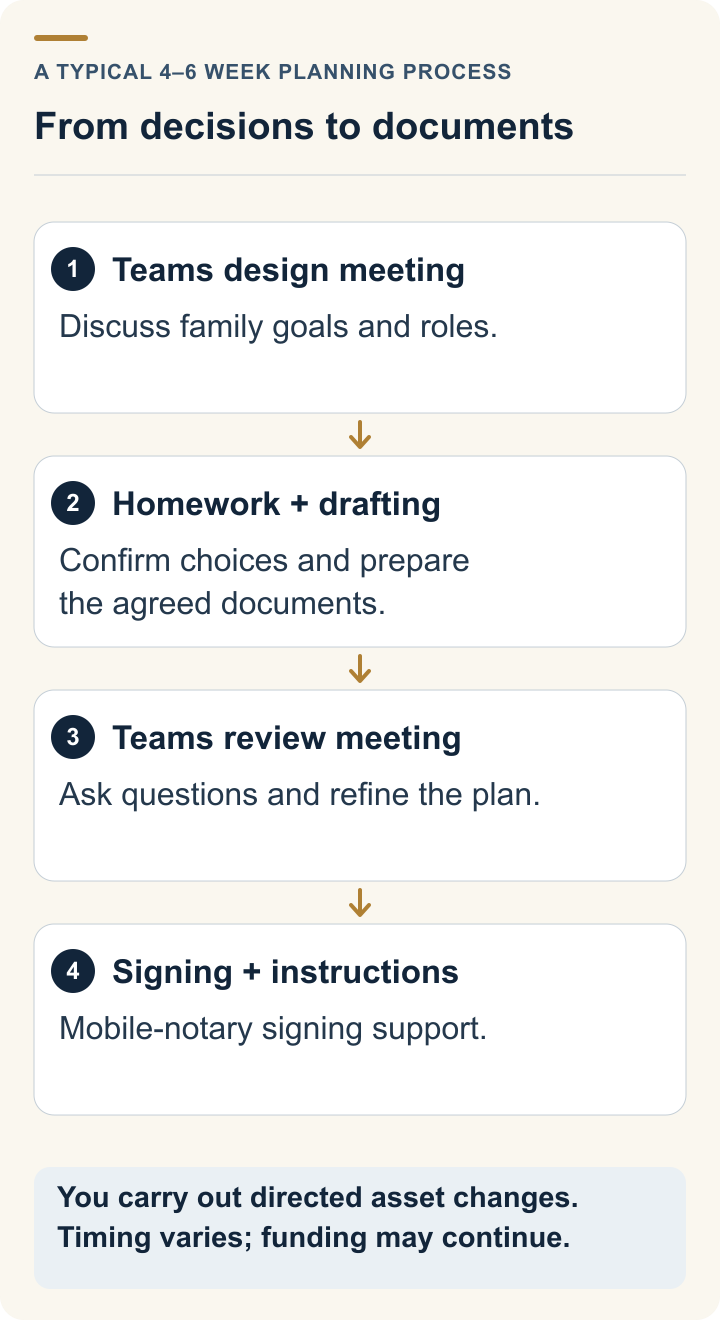
With Carolina Estate Plan, trust-based plans include first-deed/primary-residence work and detailed instructions explaining how to fund the trust with the relevant asset types. You carry out account retitling, beneficiary changes, and other asset transfers with the appropriate institutions. Retirement-account ownership and beneficiary choices require separate tax advice; do not retitle every asset the same way.
We do not perform institution-letter preparation, account-transfer completion, beneficiary updates, funding verification, a completed-funding checklist, or ongoing funding review for you. A deed included in the agreed engagement is not an unlimited commitment to handle every property you own. Confirm any additional property or unusual asset needs before engaging.
Whatever provider you choose, clarify the handoff in writing. Keep confirmations from the institutions with your own records and ask the relevant professional about an instruction you do not understand. Do not assume that signing day proves every asset has been coordinated.
Our virtual process, fees, and next steps
Carolina Estate Plan’s trust-based plans generally range from $3,500–$5,500, with the specific scope and fee confirmed for your situation. The plan includes the agreed estate-planning documents, mobile-notary signing coordination, first-deed/primary-residence work, and detailed trust-funding instructions within the scope described above.
The process typically involves two Microsoft Teams meetings, some homework, and about four to six weeks. Timing depends on completing the information and decisions needed for the plan and arranging signing; it is not a deadline guarantee. Remote planning does not mean every estate document can simply be signed in person.
Before a consultation, gather a high-level list of assets and existing documents, your preferred decision-makers and backups, and the questions that are keeping you from choosing a plan. Do not upload account passwords or complete financial account numbers into a general inquiry form.
You do not need to settle every guardian or inheritance decision before asking for advice. The point of the conversation is to work through the choices. Request a free consultation to tell us about your family and the kind of help you are seeking.
Common questions
Are online wills and trusts legal in North Carolina and South Carolina?
An online source does not by itself make a document valid or invalid. The content, capacity, applicable law, and execution or creation requirements matter. Wills, trusts, powers of attorney, and deeds should not be treated as having identical formalities. This guide is general information, not a determination that a particular document works for your situation.
Can I get attorney-guided estate planning without office visits?
Yes. Carolina Estate Plan uses Microsoft Teams for the planning meetings and coordinates mobile-notary signing. Video meetings provide access to legal advice; they do not replace the document-specific requirements for valid execution.
Is a will enough for parents with minor children?
A will can nominate a guardian and can include a trust that takes effect at death. Whether a will-based or living-trust-based plan fits your goals requires considering assets, probate, incapacity, and inheritance management. Neither a simple will nor a living trust automatically updates your insurance beneficiary designations.
Will hiring your firm mean you fund the trust for me?
No. Our trust-based plans include first-deed/primary-residence work and detailed asset-by-asset funding instructions. You handle account retitling, beneficiary updates, and other transfers. We do not provide institution letters, funding completion or verification, completed-funding checklists, or ongoing funding reviews.
What should I ask before buying a plan or legal subscription?
Ask who provides legal advice, whether they represent you, which state’s law they address, what documents and revisions are included, how signing works, and who performs each funding task. Confirm the total fee, recurring charges, access to documents, and what later updates cost. Compare the actual scope rather than relying on a package label.
General legal information for NC and SC readers. A recommendation requires review of your circumstances and the law applicable to your documents. This page does not create an attorney-client relationship.